
FINCOM Holds Decision On Recommendations Pending Further Information
One of the two petitioners supporting Article 10 on Westford’s Special Town Meeting Warrant defended the petition before the Finance Committee last Thursday. Dennis Galvin, who is also a member of the Finance Committee, laid out his case to FINCOM members, that the fiscal situation in the town was such that taxpayers at town meeting should participate participate in a decision about how Westford tax revenue are currently being applied. Galvin clarified that the petition was not being sponsored by the FINCOM.
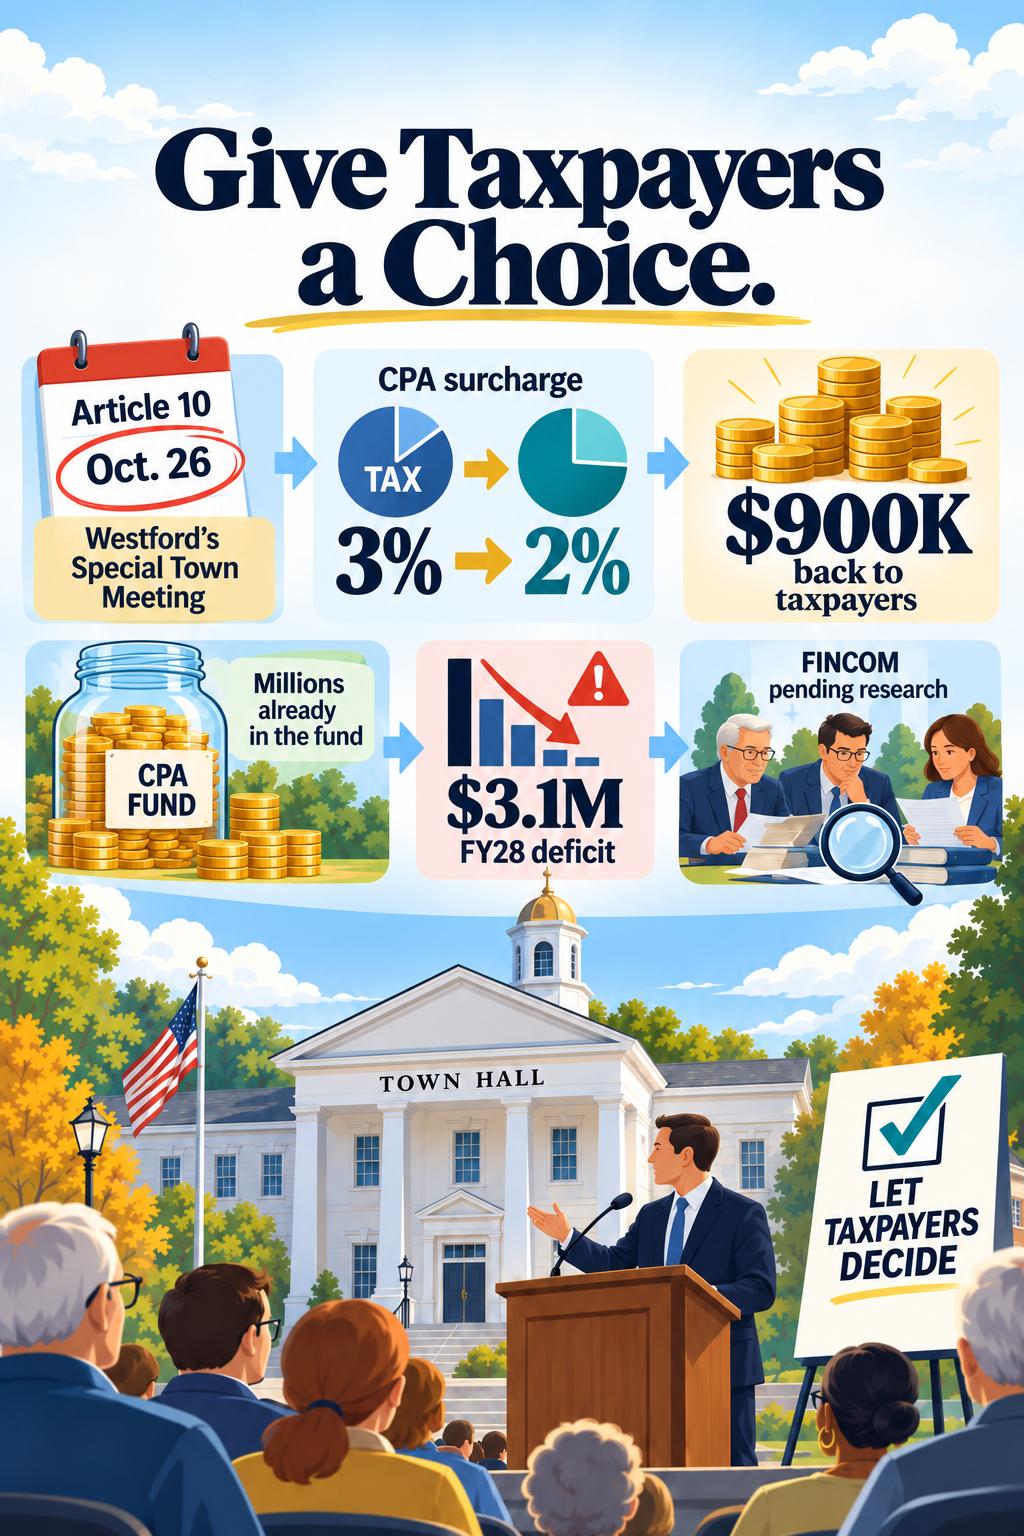
The Article 10 petition proposes to cut a 3% surcharge, which is currently assessed on Westford property owners, on their property taxes, from 3% to 2%. This cut would return 900K to the taxpayers. The surcharge, which was authorized by the 2000 Community Preservation Act passed by Beacon Hill, authorizes the surcharge in order to fund the town’s community preservation fund, which is dedicated to preserving open space, historical sites and supports affordable housing and recreational spending.
Galvin echoed warnings issued by Town Manager Kris Las, that the town was facing a structural deficit resulting from state restrictions on access to revenue and rising costs. He said that the situation will reach critical mass in FY 28, when the town is projected to face a 3.1M deficit. In his presentation Galvin revealed that in the last ten years, the CPA surcharge raised about 28M. The allotment of the funds during that period was as follows: Open Space 33%, Affordable Housing 22.5%, Historical Preservation was 10% and spending on recreation was 36%, with administrative costs rounding the total at .05% He also pointed to 4M that is currently sitting in the CPA account and the 2.5M in new revenue, that is collected by the surcharge each year stating, that some of this money could be redirected toward general fund accounts to prevent potential cuts in essential services. Galvin said that the Community Preservation Committee, which oversees the account would still take in 2% of property tax revenue, which would keep its programs viable.
Galvin was challenged in his assertions by former Select Board member and current chair of community preservation committee Bob Jeffries, who pointed out that the interruption in funding, that Galvin proposed, would effect the debt on the Roudenbush renovations. He also stated the CPA funding could also be used to fund critical renovations to schools and other town buildings. Jeffries was challenged by both Galvin and other board members over the suggestion that the funds could be used for renovations of town buildings. The ten year spending record of the fund gave no evidence of such spending. Galvin addressed the debt question by stating that of the 4M currently in the CPA account, 1.2M has been set aside for debt obligations. Galvin noted that the petition was careful to ensure that this debt would not be interrupted. The Finance Committee decided to withhold a decision on making a recommendation on the Article pending research by acting town manger Mike Edwards relative to the scope of spending of CPA money allowed by law.
Editorial
SUPPORT ARTICLE 10: GIVE TAXPAYERS A CHOICE
Westford struggles with a “structural deficit” caused by two factors; proposition 2 ½, and increasing costs. Proposition 2 ½ limits property tax increases to 2 ½ per cent over the previous year’s tax levy, a vital protection for taxpayers. However, the issue of increasing costs is also very real. The cost of energy, vendor services and benefit costs for town employees and retirees are skyrocketing. Add in recently settled employee contracts and expensive public building projects and you have a budget crisis. Recent estimates show the town facing a 3.1M deficit in FY 28.
Article 10 on the warrant for the October 26th special town meeting, offers property owners a choice, which could allow them to address these rising costs, while easing the pain caused by tax hikes. It calls for a 1% roll back in the Community Preservation surcharge, a town-imposed fee on property owners above their actual tax assessment. The revenue from this surcharge goes to the CPA fund to support open space and historic preservation, affordable housing and recreation. The CPA is a dedicated fund; it cannot be used for general budget items. The surcharge authorized by the Community Preservation Act, passed in 2001, is a local option. Westford opted in at the highest rate of 3%. Taxpayers have been paying this for twenty years. State matching funds, once part of the deal, have significantly dwindled over the years. State money is spreading thin.
The town’s current CPA balance is 4.4M. 1.2M is encumbered for debt obligations, leaving 3.2M in available funds. Under the current 3% surcharge the town receives 2.5M annually to support the fund. A 1% roll back would reduce the annual take to 1.6M, which is still sufficient to maintain CPA initiatives. It would also return 900K back to the taxpayers.
The CPA rollback gives Westford taxpayers an interesting choice. Because the CPA is funded through the same revenue stream as the town’s operating budget, which is the property tax, a rollback could free up potential revenue without having to increase taxes. The rollback would return 900K to taxpayers. They could then decide whether to keep the money to soften an pendng tax hike from an expected increase in the excluded debt assessment for the library renovations, or transfer it through an override process to the general fund increasing discretionary revenue. In both cases no new taxation would be needed. Support the CPA rollback, it is good stewardship and it gives taxpayers an important choice in meeting the town’s growing budget challenge.
Leave a Reply